Understanding Marginal Costs
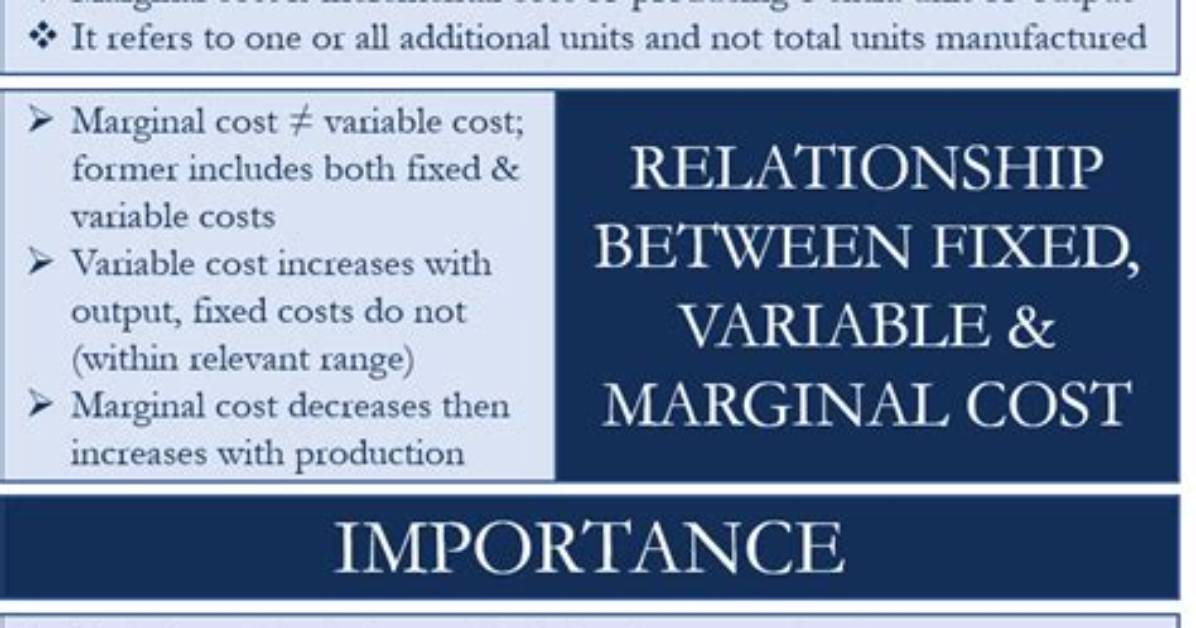
Marginal costs are a function of the total cost of production, which includes fixed and variable costs.
What is included in marginal cost?
Marginal cost refers to the additional cost to produce each additional unit. For example, it may cost $10 to make 10 cups of Coffee. To make another would cost $0.80. Therefore, that is the marginal cost – the additional cost to produce one extra unit of output. Marginal cost comes from the cost of production.
Is fixed cost included in total cost?
Total costs are composed of both total fixed costs and total variable costs. Total fixed costs are the sum of all consistent, non-variable expenses a company must pay.

