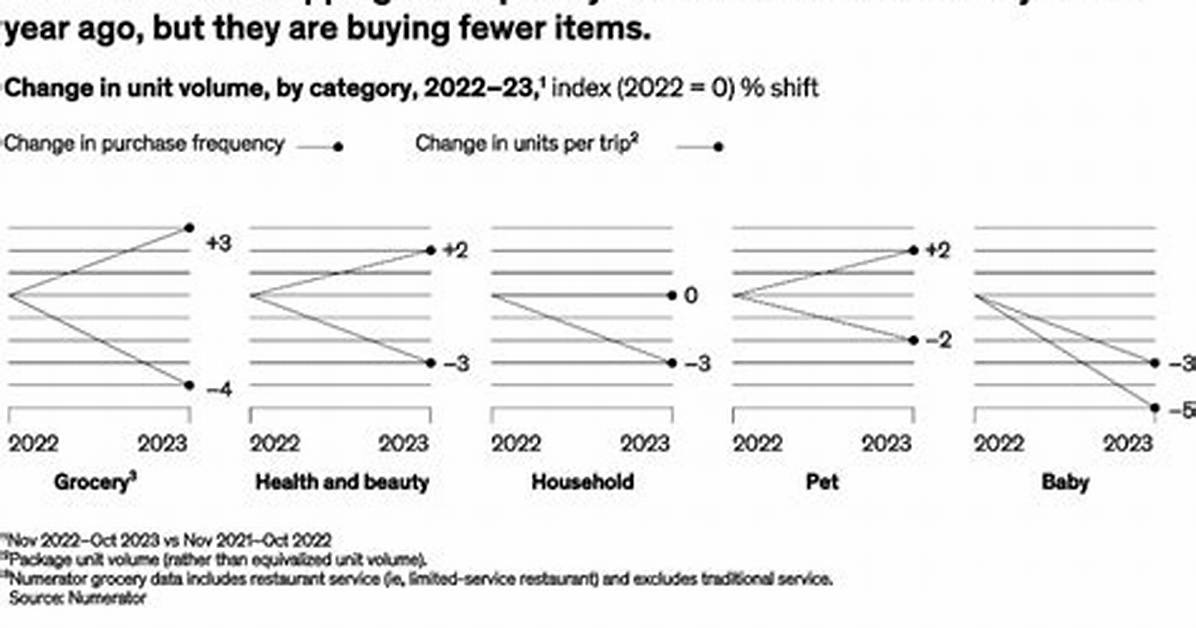
Despite a relatively strong economy and low unemployment, consumers are buying fewer items—and spending more to do so. The volume declines in consumer packaged goods (CPG) are dramatic, especially considering the growth that occurred in the early days of the COVID-19 pandemic.
The volume decline is pervasive across categories, from grocery to personal care and household products. US CPG volume declined 2 to 4 percent on average, with larger subcategories such as vitamins and supplements suffering 5 percent declines compared with 2022 figures. Even the holiday season wasn’t enough to open a proverbial parachute: grocery volume declined 2 percent in November and December 2023, compared with the same period the year before.
This is happening even as consumers increase their shopping frequency across most channels and categories, creating a confusing set of circumstances for CPG brands to navigate.
In this article, we dive into the specifics of the recent CPG volume declines, examine McKinsey research to understand why consumer behaviors are shifting, and explore what this means for US CPG businesses in 2024.
Consumers are shifting their behavior in small but meaningful ways
We have identified two primary ways that consumer behavior has shifted. First, consumer purchase occasions occurred at the same—and in some cases, at a higher—frequency than in 2022, but consumers purchased fewer items on each trip (Exhibit 1). Units per trip declined by 3 to 5 percent across the grocery, health and beauty, and household categories, outweighing the growth in frequency of purchase occasions (up by no more than 3 percent) in the same categories. (For more on how grocery volumes could shift, see sidebar, “Are GLP-1s affecting consumer spending?”)
But among the volume declines, there were green shoots: Gen Z consumer purchase occasions for grocery and health and beauty products increased 10 percent in 2023, compared with 2022 (although with slightly fewer units purchased on each occasion). That means Gen Zers, on average, went grocery shopping one to two additional times per month and shopped for health and beauty products one additional time every other month in 2023.
Analyzing five consumer goods categories across five sales channels, we see that consumers shifted their spend away from traditional brick-and-mortar channels and toward online and value channels (Exhibit 2). Still, the volume losses in brick-and-mortar outweighed the volume gains made in online and select value channels.
Among the channels analyzed, grocery items sold through food channels and all categories sold through mass channels represent the largest volumes in consumer goods—and suffered the biggest declines in 2023, along with drug stores. Comparatively, four out of five categories of CPG found volume growth online. The dollar channel demonstrated mixed results, with increases in grocery and pet segments but decreases in household and baby units.
Amid the general downturn, however, there were pockets of resilience. Online unit sales, for example, consistently grew by more than 4 percent. Among Gen Z consumers, this shift is even more pronounced: online unit sales from these consumers increased at nearly two times the rate of increases in online unit volume for other generations. Gen Z also helped cushion volume declines in mass and dollar store channels.
Consumers are feeling the effect of higher prices
There’s plenty of speculation about what’s fueling consumer goods volume declines. When we asked consumers why their shopping behaviors changed last year, one thing was clear: prices weighed on their decision making. Consumers cited product price hikes and their ability to afford something (whether for personal or economic reasons) as the key drivers behind purchasing fewer items across categories (Exhibit 3).
Increased prices were the number-one reason consumers reported purchasing fewer items in grocery, personal care, and household products. This also appeared to be the case across subcategories such as beverages, snacks, dairy products, cereals, and fresh and prepared foods.
Consumers said they also reduced the number of items they purchased because they were waiting for them to go on sale. Among shoppers we surveyed who said they anticipate reducing the number of purchases they make in the next six months, roughly 40 percent cited affordability constraints due to “economic reasons.”
Although it accounted for a smaller share of responses than price or affordability, stocking up on goods in 2022 meant consumers made fewer purchases in personal-care and household categories in 2023 (this was particularly evident among baby boomers). Meanwhile, consumers said they bought fewer discretionary items, sticking to essential purchases instead. This echoes the findings in our earlier ConsumerWise research, in which consumers—often led by Gen Xers—said they also planned to spend less money on discretionary items in the coming months. (By comparison, Gen Zers reported a higher intent to spend than the average consumer across most categories our research tracked.)

