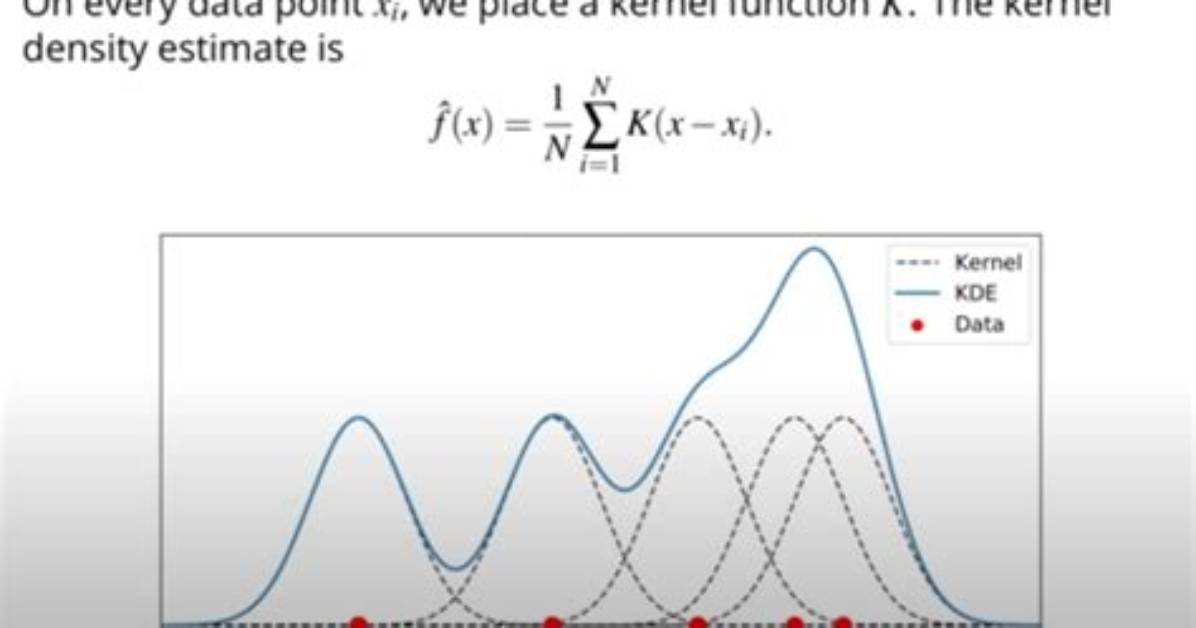
In statistics, kernel density estimation is a non-parametric way to estimate the probability density function of a random variable. Kernel density estimation is a fundamental data smoothing problem where inferences about the population are made, based on a finite data sample.
How do you calculate kernel density?
Kernel Density Estimation (KDE)
It is estimated simply by adding the kernel values (K) from all Xj. With reference to the above table, KDE for whole data set is obtained by adding all row values. The sum is then normalized by dividing the number of data points, which is six in this example.
What is a kernel in kernel density estimate?
While a histogram counts the number of data points in somewhat arbitrary regions, a kernel density estimate is a function defined as the sum of a kernel function on every data point. The kernel function typically exhibits the following properties: Symmetry such that K ( u ) = K ( − u ) .

