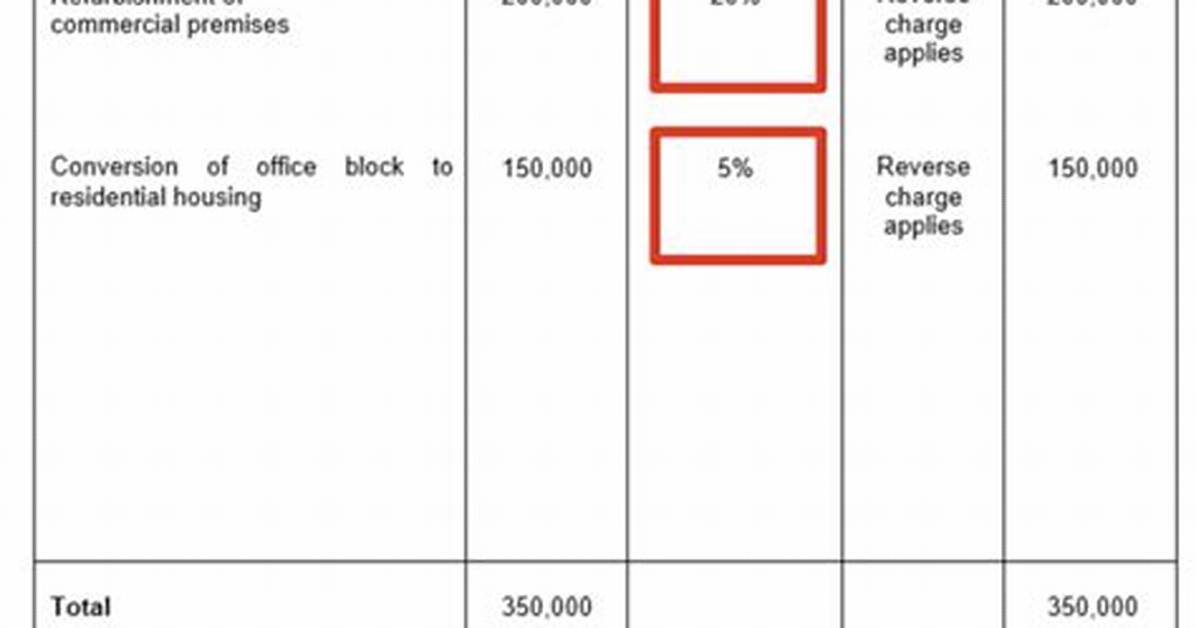
As a general rule, businesses charge VAT on supplies and deduct VAT on purchases. The reverse charge mechanism is a deviation from this rule where the supplier does not charge VAT on the invoice and the customer pays and deducts VAT simultaneously through the VAT return.
How does VAT reverse charge work?
VAT reverse charge means that customers are able to charge themselves VAT and pay it directly to HM Revenue and Customs (HMRC) rather than the supplier sending them an invoice at a later date, which in return stops suppliers from avoiding paying HMRC, also known as missing trader fraud.
Do you pay VAT on reverse charge?
As the reverse charge makes it the customer's responsibility to account for VAT there is no opportunity for the supplier to disappear without paying the VAT to HMRC.

