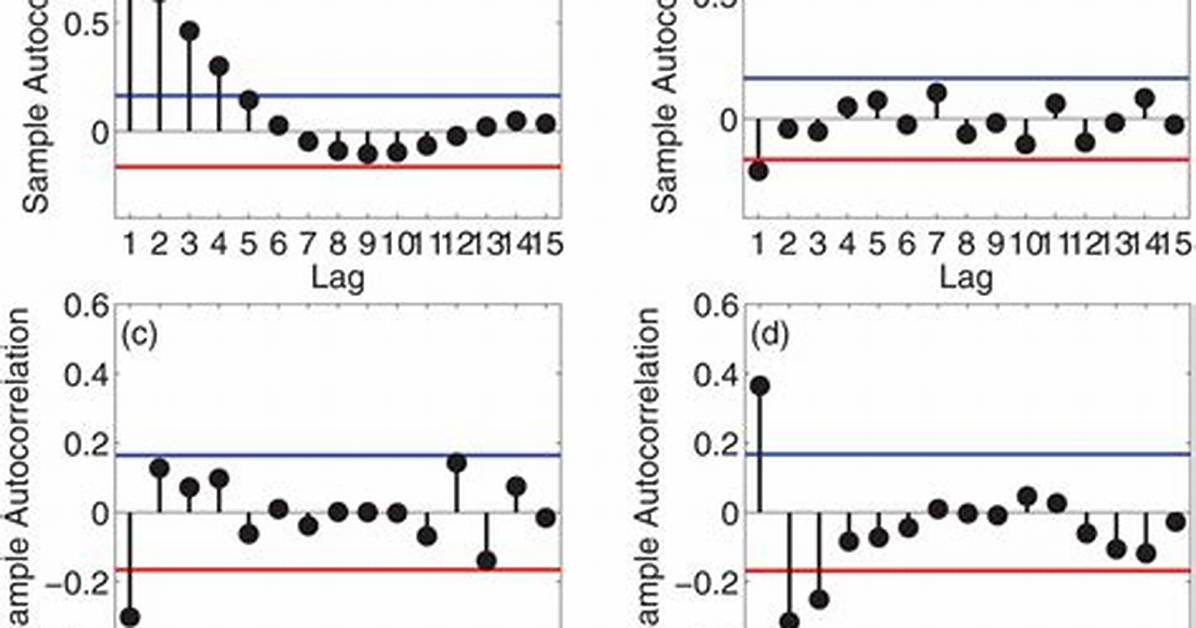
Does first differencing reduce autocorrelation? ... First differencing reduces the absolute value of the autocorrelation coefficient when ρ is greater than 1/3. For economic data, this is likely to be fairly common.
Does differencing remove autocorrelation?
Differencing tends to introduce negative correlation: if the series initially shows strong positive autocorrelation, then a nonseasonal difference will reduce the autocorrelation and perhaps even drive the lag-1 autocorrelation to a negative value.
What are the consequences of autocorrelation on the OLS estimator?
The OLS estimators will be inefficient and therefore no longer BLUE. The estimated variances of the regression coefficients will be biased and inconsistent, and therefore hypothesis testing is no longer valid. In most of the cases, the R2 will be overestimated and the t-statistics will tend to be higher.

