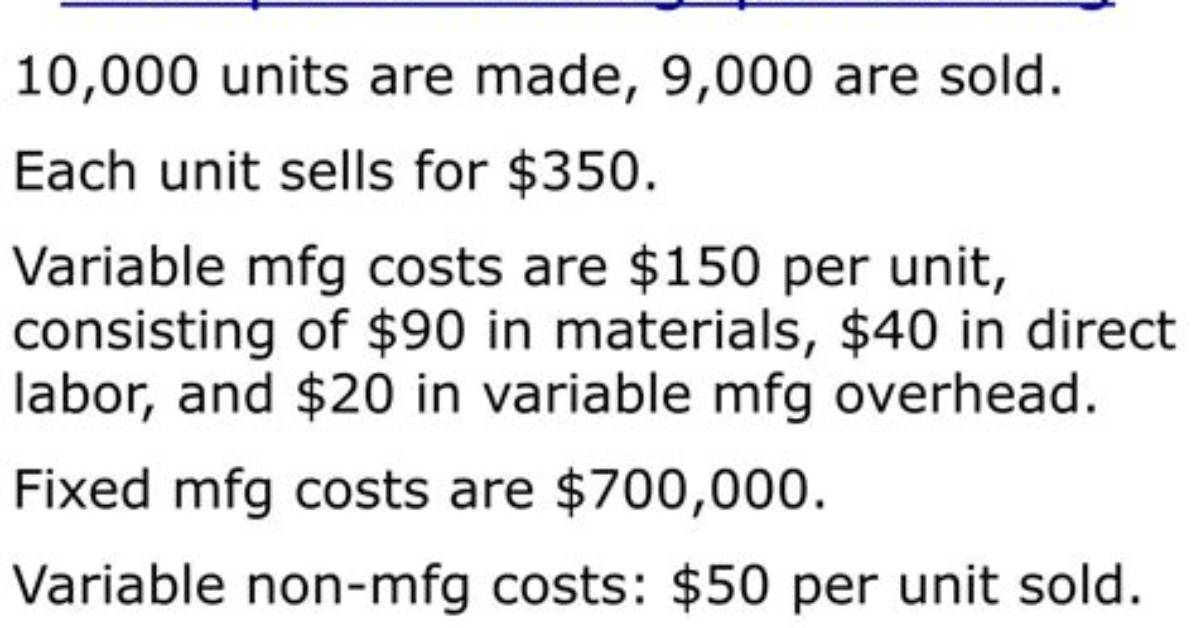
Throughput costing is also known as super-variable costing. Throughput costing considers only direct materials as true variable cost and other reaming costs as period costs to be charged in the period in which they are incurred. Thus, in throughput costing, only direct materials costs are inventoriable costs.
When should throughput costing be used?
Throughput costing treats all costs as period expenses except for direct materials. It is also called super-variable costing. It is very suitable for those companies where labor and overheads are fixed costs.
How is throughput cost calculated?
Throughput is calculated as 'selling price less direct material cost. ' This is different from the calculation of 'contribution', in which both labour costs and variable overheads are also deducted from selling price.

