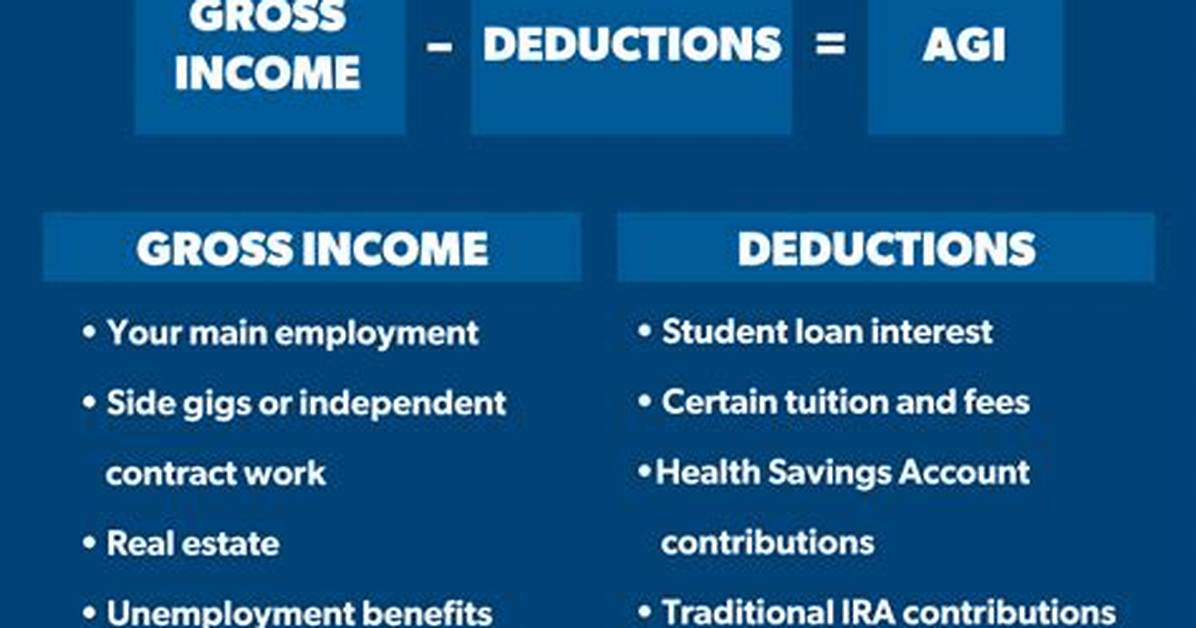
To get taxable income, take your AGI and subtract either the standard deduction or itemized deductions and the qualified business income deduction, if applicable. If your AGI is high enough, you become ineligible for certain tax deductions or credits. A fancy tax term for this is that they have an “AGI threshold.”
Is AGI before or after standard deduction?
Your AGI is calculated before you take the standard or itemized deductions —which you report in later sections of the return.
What reduces your adjusted gross income?
Reduce Your AGI Income & Taxable Income Savings
- Contribute to a Health Savings Account. ...
- Bundle Medical Expenses. ...
- Sell Assets to Capitalize on the Capital Loss Deduction. ...
- Make Charitable Contributions. ...
- Make Education Savings Plan Contributions for State-Level Deductions. ...
- Prepay Your Mortgage Interest and/or Property Taxes.

