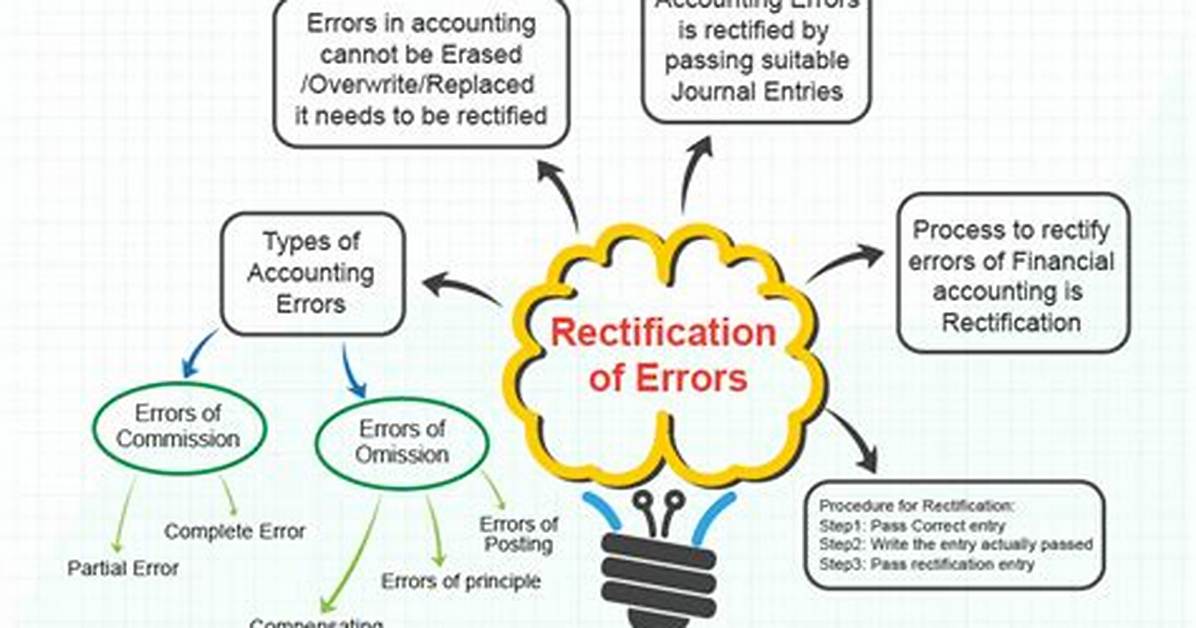
Definition: Rectification of errors is a procedure of revising mistakes in the entries. These errors can be of two types, i.e, the errors committed on both sides in an entry that does not influence the trial balance and can be rectified by making a journal entry.
How do you solve rectification errors?
We can rectify these by passing a journal entry giving the correct debit and credit to the accounts. In order to rectify an error, we need to cancel the effect of wrong debit or credit by reversing it and restore the effect of correct debit or credit.
What is the need for rectification of errors?
Whenever an error occurs, it should be rectified through proper rectification. Otherwise the books of accounts cannot exhibit the true and correct view of the state of affairs of a business and its financial results. So it is very important that we identify and rectify all material errors in the books of accounts.

