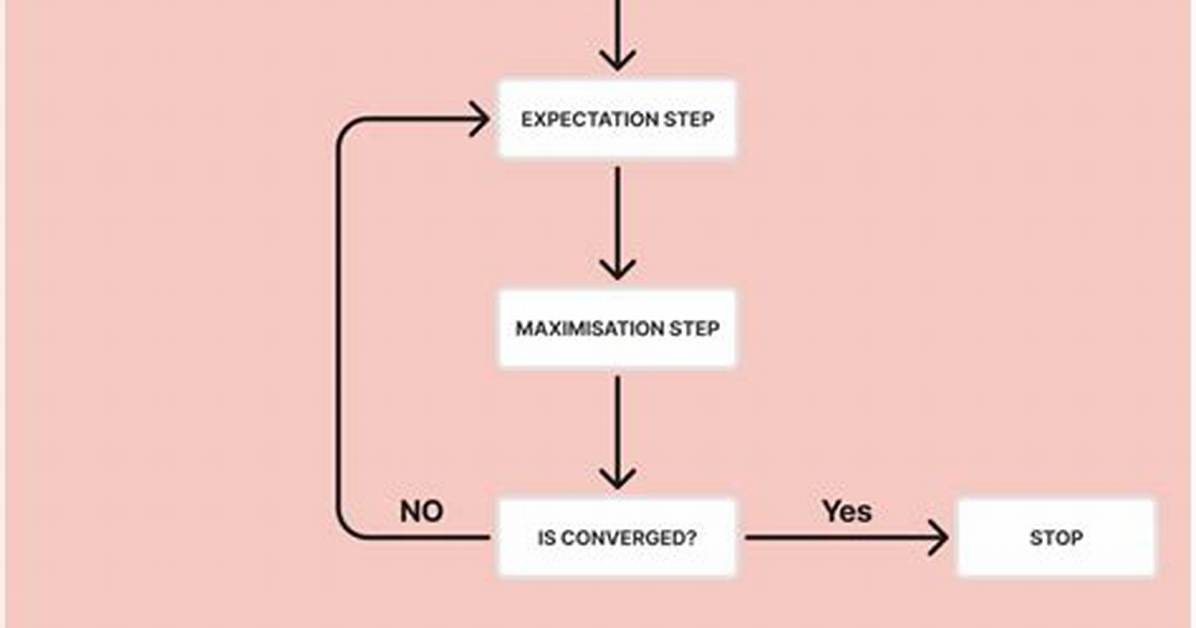
In statistics, an expectation–maximization algorithm is an iterative method to find maximum likelihood or maximum a posteriori estimates of parameters in statistical models, where the model depends on unobserved latent variables.
What is EM algorithm in machine learning?
The Expectation-Maximization Algorithm, or EM algorithm for short, is an approach for maximum likelihood estimation in the presence of latent variables. A general technique for finding maximum likelihood estimators in latent variable models is the expectation-maximization (EM) algorithm.
What is the EM algorithm used for?
The EM algorithm is used to find (local) maximum likelihood parameters of a statistical model in cases where the equations cannot be solved directly. Typically these models involve latent variables in addition to unknown parameters and known data observations.

