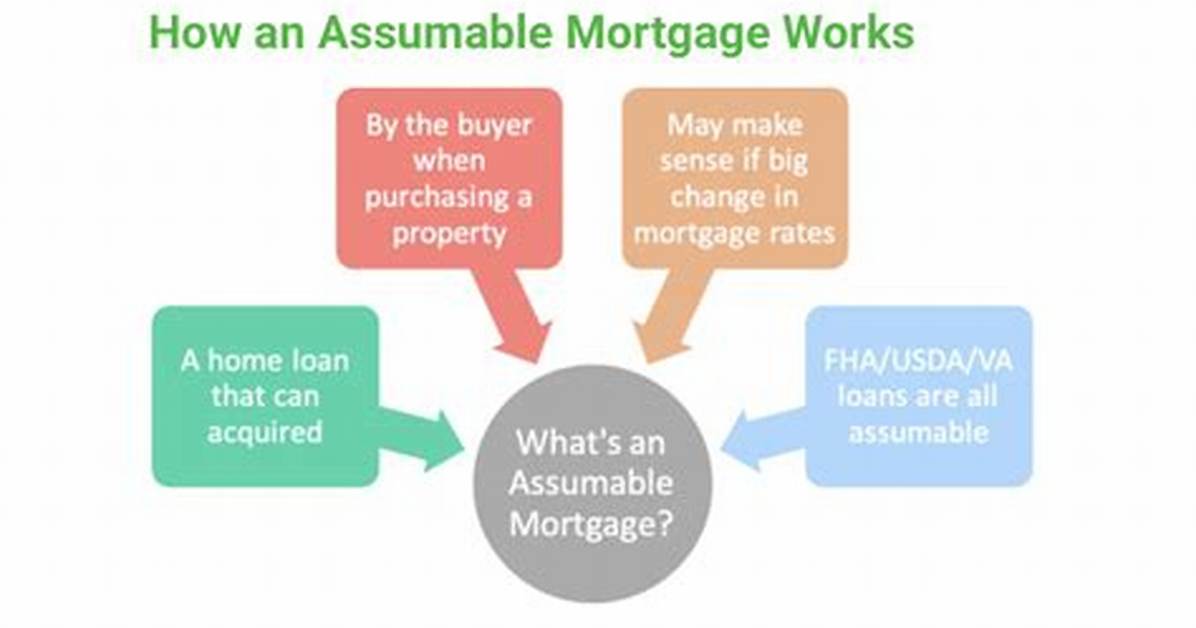
Mortgage assumption is the conveyance of the terms and balance of an existing mortgage to the purchaser of a financed property, commonly requiring that the assuming party is qualified under lender or guarantor guidelines.
How does an assumable loan work?
An assumable mortgage allows a buyer to take over the seller's mortgage. Once the assumption is complete, you take over the payments on a monthly basis, and the person you assume the loan from is released from further liability. If you assume someone's mortgage, you're agreeing to take on their debt.
How do I know if my mortgage is assumable?
You can check the loan documents to see whether assumptions are permitted. The loan document will typically state whether or not the loan is assumable under the "assumption clause." The terms may also appear under the "due on sale clause" if loan assumption isn't permitted.

