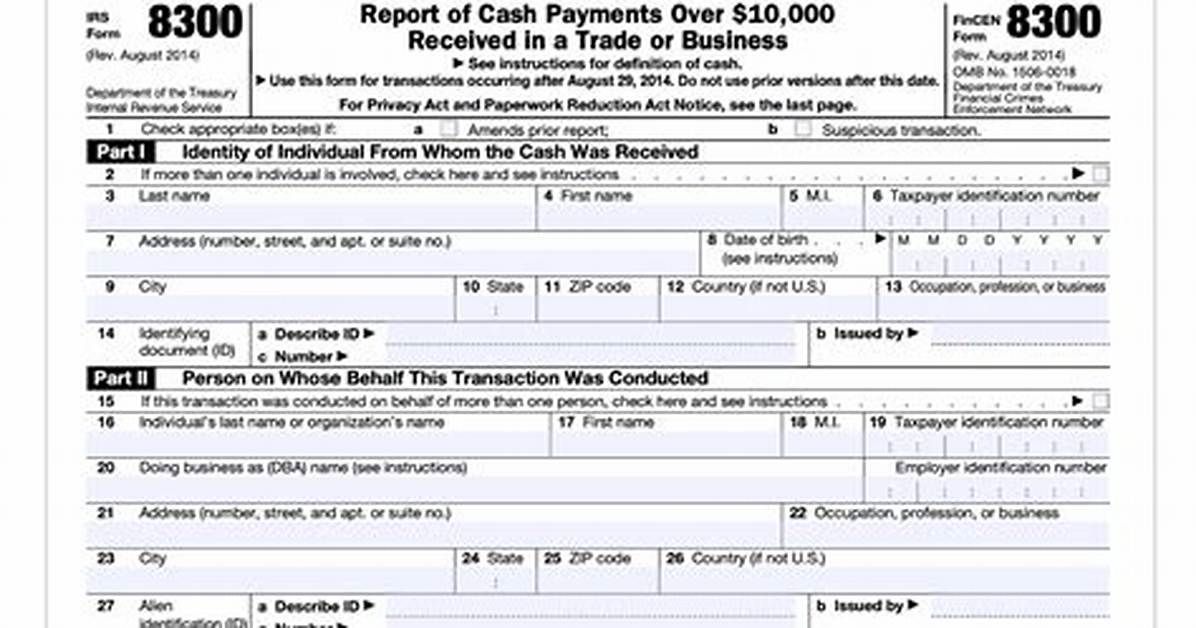
Subsequently, one may also ask, what does the IRS do with form 8300?
IRS Form 8300 is Report of Cash Payments Over $10,000 Received in a Trade or Business. It is used to help prevent money laundering. You do not report it on your tax return.
Secondly, how do I stop Form 8300? Here are five suggestions to keep you out of your local IRS auditor's office.
- File Online. The IRS has capabilities for you to file Form 8300 online.
- Keep Copies for Five Years.
- You Must File Within 15 Days of Receiving the Money.
- Create and Send Customer Statements.
- Understand Which Transactions Count.
In this way, what triggers an IRS audit?
You Claimed a Lot of Itemized Deductions The IRS expects that taxpayers will live within their means. It can trigger an audit if you're spending and claiming tax deductions for a significant portion of your income. This trigger typically comes into play when taxpayers ?itemize.
Who fills out form 8300?
Generally, any person in a trade or business who receives more than $10,000 in cash in a single transaction or in related transactions must file a Form 8300. Persons includes an individual, a company, a corporation, a partnership, an association, a trust, or an estate.
Does IRS look at bank accounts?
What happens when you deposit over $10000?
How much money is suspicious to deposit?
Does IRS know your income?
Can I deposit 50000 cash in bank?
Does the IRS know when you buy a car?
Are wire transfers over $10000 reported to the IRS?
How much cash can you withdraw without reporting to IRS?
What are red flags for IRS audit?
How do I survive an IRS audit?
- Don't ignore the notice. You generally have 30 days to respond to an audit notice.
- Read and follow the notice.
- Organize your records.
- Replace missing records.
- Bring only what you're asked for.
- Don't be a jerk!
- Provide only copies.
- Stay on point.
What happens if you fail an IRS audit?
What are the red flags for IRS audit?
Others, such as high income, can't be helped.
- Not reporting all of your income.
- Breaking the rules on foreign accounts.
- Blurring the lines on business expenses.

