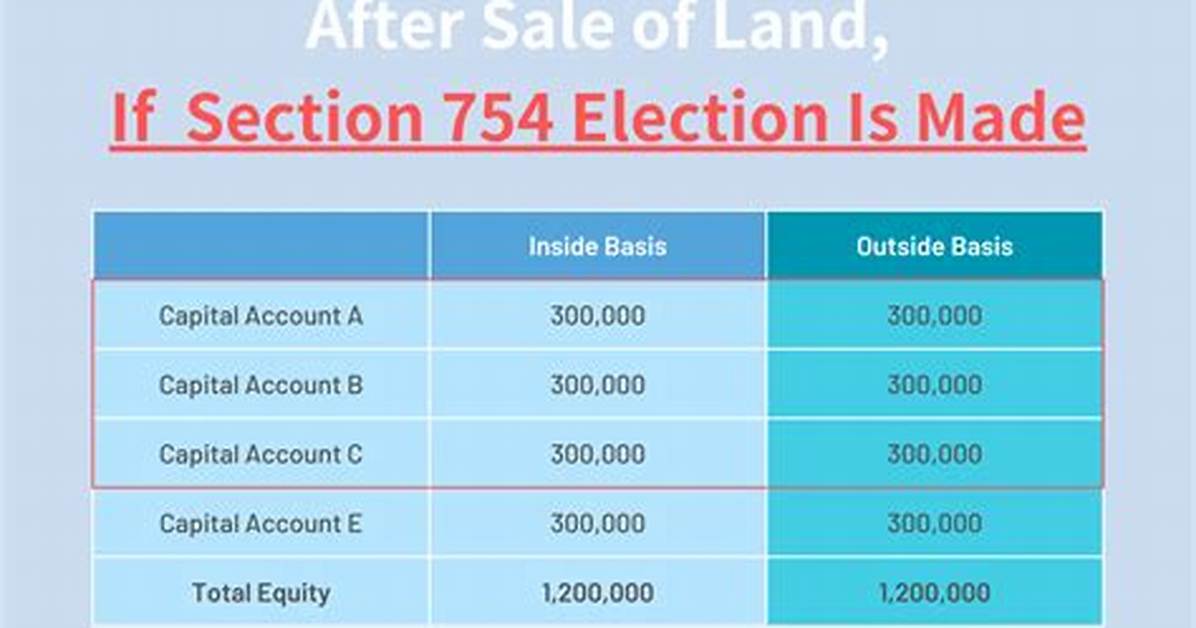
When should you make a 754 election?
How to elect? If the partnership decides they want the step-up they must make the 754 election. It must be made before the due date of the income tax return, including extensions, for the year that the transfer occurs.
Is section 754 included in tax basis?
However, Sections 734 and 754 adjustments related to transactions with the partnership are included in TBM. Notice 2021-13 reiterates the four permitted methods that the draft instructions state must be used to calculate beginning tax basis capital. If the partnership has been using TBM, it can simply continue.
How do I report a Section 754 depreciation?
Indicate an amount of §754 depreciation using one of the following methods:
Select 754 from the drop list in the For: field on the 4562 screen, or.Enter the amount directly on screen DED. Enter the amount of §754 depreciation on line 16b (“Depreciation claimed elsewhere on return”), or.Open screen K.
What is 754 step up basis?
Adjusting basis of partnership assets, for an increase in value, is elective (i.e., IRC 754 Election). When a step-up occurs, the basis in the partnership’s assets are adjusted according to relative unrealized/built-in gain of the assets.
Does 743 B adjustment affect tax basis?
basis adjustments – Section 743(b) basis adjustments are not taken into account in calculating a partner’s tax basis capital.
Can a single member LLC make a 754 election?
The regulations make clear that only a partner may sign a valid Sec. 754 election (Regs. Sec. 1.754-1(b)).
Can an S Corp make a 754 election?
This election and tax savings opportunity is not available to S corporations; S corporations may not make Section 754 elections.
How is Section 754 elected?
754 election must (1) set forth the name and address of the partnership making the election, (2) be signed by any one of the partners, and (3) contain a declaration that the partnership elects under Sec. 754 to apply the provisions of Secs.
What is inside vs outside basis?
Partnership tax law often refers to “outside” and “inside” basis. Outside basis refers to a partner’s interest in a partnership. Inside basis refers to a partnership’s basis in its assets.
What is outside basis S corporation?
It is not the corporation’s responsibility to track a shareholder’s stock and debt basis but rather it is the shareholder’s responsibility. The stockholder basis is referred to as outside basis which is different than the company equity or retained earnings.
What is inside and outside basis?
The inside basis is the partnership’s tax basis in the individual assets. The outside basis is the tax basis of each individual partner’s interest in the partnership. When a partner contributes property to the partnership, the partnership’s basis in the contributed property = its fair market value ( FMV ).
Where does Section 754 depreciation go on k1?
Section 754 and 743(b) depreciation is usually used to reduce the income reported on the K-1 from the partnership side. A section 754 depreciation adjustment reported on the supplemental information page of a K-1 doesn’t usually need to be reported anywhere on the individual tax return.
Does Section 754 depreciation reduce tax basis?
On an Income-tax Return
The total Section 754 adjustment of $50,000 is reduced to zero over time using the same mechanics as the depreciation on the building. The 754 adjustment reduces both Carl’s inside and outside basis equally.
What is 721 C property?
The IRC 721(c) regulations generally provide that a U.S. Transferor must recognize gain upon the transfer of appreciated property (tangible or intangible property) to certain partnerships (domestic or foreign) whose partners include foreign persons related to the U.S. Transferor unless certain requirements are met.

