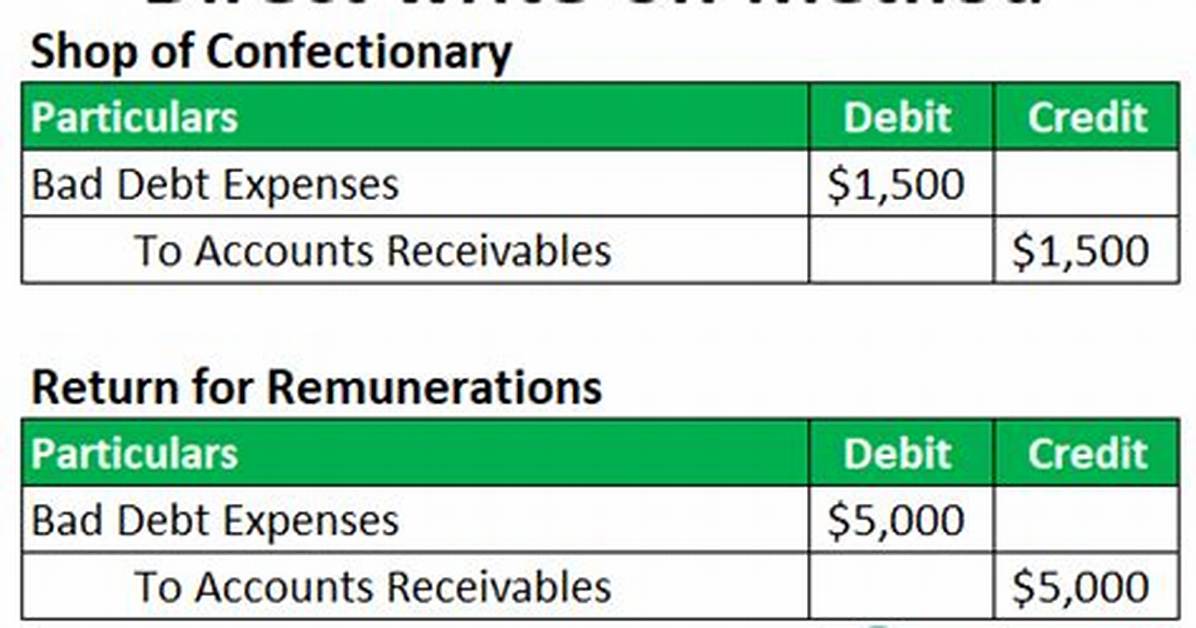
Under the direct write-off method, a bad debt is charged to expense as soon as it is apparent that an invoice will not be paid. Under the allowance method, an estimate of the future amount of bad debt is charged to a reserve account as soon as a sale is made.
Is direct write-off method allowed?
What Is Wrong with the Direct Write off Method? The direct write off method violates GAAP, the generally accepted accounting principles. GAAP says that all recorded revenue costs must be expensed in the same accounting period. This is called the matching principle, according to Accounting Tools.
Is the direct write-off method GAAP?
The direct write off method doesn’t comply with the GAAP, or generally accepted accounting principles. GAAP states that expenses and revenue must be matched within the same accounting period.
Why is direct write-off method appropriate?
Advantages of the direct write-off method
The direct write-off method is considered an easy way to deal with bad debts because you only need to make two transactions—one to the bad debts expenses account and the other to accounts receivable for the amount the customer owes.
How do you record a write-off in accounting?
The entry to write off the bad account under the direct write-off method is:
Debit Bad Debts Expense (to report the amount of the loss on the company’s income statement)Credit Accounts Receivable (to remove the amount that will not be collected)
What is direct write-off method quizlet?
direct write-off method. a method of accounting for uncollectible receivables in which the company records bad debts expense when a customer’s account receivable is uncollectible. dishonor a note. failure of a note’s maker to pay a note receivable at maturity.
Why is direct write-off method bad?
The direct write off approach violates the matching principle, under which all costs related to revenue are charged to expense in the same period in which you recognize the revenue, so that the financial results of an entity reveal the entire extent of a revenue-generating transaction in a single accounting period.
What is the normal balance for bad debt expense?
Because the allowance for doubtful accounts account is a contra asset account, the allowance for doubtful accounts normal balance is a credit balance.
How do companies account for bad debt?
A company will debit bad debts expense and credit this allowance account. The allowance for doubtful accounts is a contra-asset account that nets against accounts receivable, which means that it reduces the total value of receivables when both balances are listed on the balance sheet.
When can you write-off accounts receivable?
You can’t write the receivables off until you give up on collecting the debts. You can base your IRS write-offs on aging of accounts, which means counting how long they’ve been outstanding.
Why is the direct write-off method generally not permitted for financial reporting purposes?
The direct write-off method is used for tax purposes but is generally not permitted for financial reporting. A firm must use the allowance method if it is probable that the firm will not collect a material amount of receivables ad it can reasonably estimate that amount.
What does it mean to write-off in accounting?
A write-off is an elimination of an uncollectible accounts receivable recorded on the general ledger. An accounts receivable balance represents an amount due to Cornell University. If the individual is unable to fulfill the obligation, the outstanding balance must be written off after collection attempts have occurred.
How do you do a write-off?
To qualify for a write-off, the IRS uses the terms “ordinary” and “necessary;” that is, an expense must be regarded as necessary and appropriate to the operation of your type of business. Generally, tax write-offs fit into specific reporting categories such as business travel, advertising, or home office expenses.
Is a write-off an expense?
A write-off is a business expense that reduces taxable income on the income statement. A write-off is different from a write-down, which partially reduces (but doesn’t totally eliminate) an asset’s book value.

