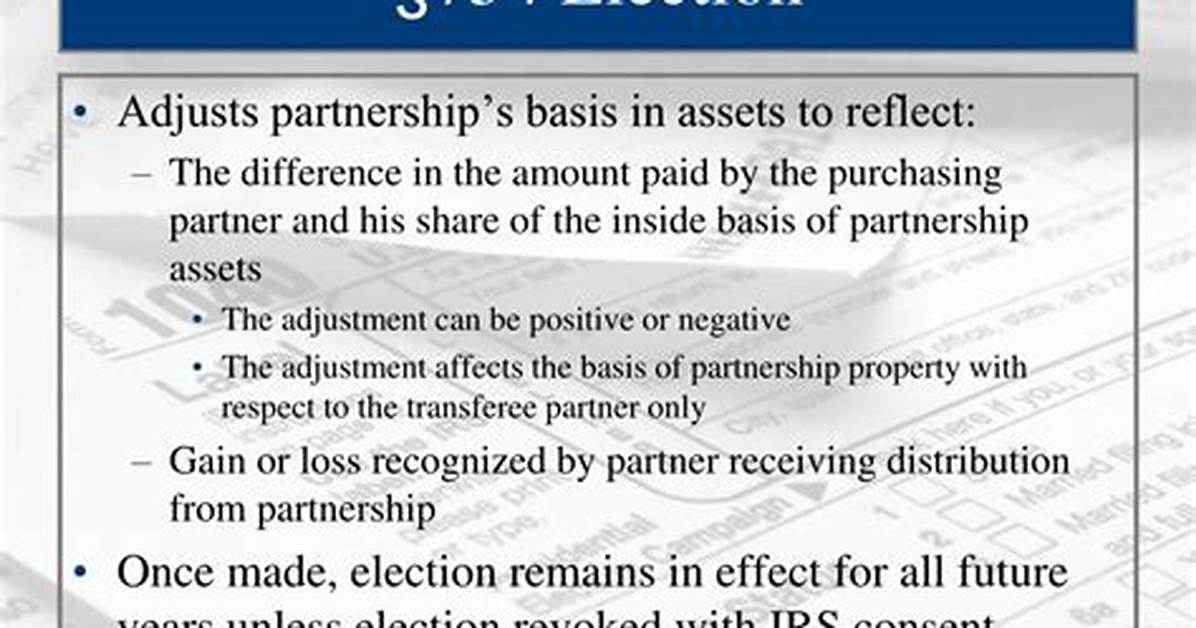
If the partnership decides they want the step-up they must make the 754 election. It must be made before the due date of the income tax return, including extensions, for the year that the transfer occurs.
What is a 754 asset?
Section 754 of the Internal Revenue Code (IRC) deals with complex issues that often arise in connection with assets owned by a partnership. Under Section 754, a partnership may adjust the basis of partnership property when the property is distributed or when a partnership interest is transferred.
What happens if you don’t make a 754 election?
If no 754 Election is made when D purchases A’s one-third interest in Partnership Z, Partnership Z’s inside basis is unaffected, and D’s one-third share of the inside basis is $180,000. On the sale of the building, each partner (including D) recognizes one third of the $960,000 gain, or $320,000 each.
How do you make a 754 adjustment?
754 election must (1) set forth the name and address of the partnership making the election, (2) be signed by any one of the partners, and (3) contain a declaration that the partnership elects under Sec. 754 to apply the provisions of Secs.
Can a single member LLC make a 754 election?
754 elections are invalid because they are filed with the wrong partnership tax return. According to Regs. Sec. 1.754-1(b), a Sec.
Can an S Corp make a 754 election?
This election and tax savings opportunity is not available to S corporations; S corporations may not make Section 754 elections.
Does 754 depreciation reduce basis?
On an Income-tax Return
The total Section 754 adjustment of $50,000 is reduced to zero over time using the same mechanics as the depreciation on the building. The 754 adjustment reduces both Carl’s inside and outside basis equally.
Does 754 affect tax basis?
754 Adjustments to Basis
As a result of operations, the basis that a partner has in his or her partnership interest will fluctuate throughout the term of the partner’s ownership.
What is the difference between 743 b and 754?
Sec. 743(b) provides that in the case of a sale or exchange of a partnership interest for which a Sec. 754 election is in place, a partnership shall adjust the basis of partnership property.
What triggers a 754 election?
An IRC Section 754 election allows a partnership to adjust the basis of the property within a partnership under IRC Sections 734(b) and 743(b) when one of two triggering events occur: 1) a distribution of partnership property or 2) certain transfers of a partnership interest.
What is outside basis vs inside basis?
The inside basis is the partnership’s tax basis in the individual assets. The outside basis is the tax basis of each individual partner’s interest in the partnership. When a partner contributes property to the partnership, the partnership’s basis in the contributed property = its fair market value ( FMV ).
What is 743b adjustment?
743(b) adjustment by a partnership generally hinges on the partnership’s receiving written notice of a sale or exchange or of a transfer upon the death of the partner. Thus, transferees have a duty to report transfers promptly to their partnership.
What is 721 C property?
The IRC 721(c) regulations generally provide that a U.S. Transferor must recognize gain upon the transfer of appreciated property (tangible or intangible property) to certain partnerships (domestic or foreign) whose partners include foreign persons related to the U.S. Transferor unless certain requirements are met.
What are hot assets?
Definition: Hot assets are business assets that have the potential of built in ordinary income. In other words, these are assets that would generate ordinary income if sold. The main two examples are inventory and accounts receivable.
Does the death of a partner cause a technical termination?
Accordingly, the partnership’s tax year closes for all partners on the date of death. The death of a partner in a two-person partnership will terminate the partnership for federal tax purposes if it results in the partnership’s immediately winding up its business (Sec.
What happens when a partnership buys out a partner?
Partnership buyouts that include deferred payouts generally provide more benefits to the departing partners than to those remaining. When payments are received in multiple years, the departing partner should be able to recover the full tax basis before having to recognize any capital gains.
Can you take bonus on 754 Step Up?
Basis adjustments under §734(b) do not qualify for 100-percent bonus depreciation. However, if a §754 election is in effect, a basis step-up under §743(b) will qualify for 100-percent bonus depreciation if the transaction is between unrelated partners.
Recommended Posts
wie bekommt man spinnenkot weg ueberpruefen sie es spinnenkot flecken
wird kfw studienkredit in schufa eingetragen ueberpruefen sie es kfw studienkredit schufa
welcher nagellack ist am besten bei bruechigen naegeln ueberpruefen sie es bester nagelhaerter
wie bekomme ich benutzer identifikation fuer den einstieg in finanzonline siehe dort benutzeridentifikation finanzamt beantragen
wie viel passionsfrucht am tag ueberpruefen sie es ist passionsfrucht gesund
where is whatsapp illegal siehe dort whatsapp illegal
warum kann ich keine bilder mehr downloaden siehe dort whatsapp probleme bilder download
wie wird ein balkon saniert siehe dort wie teuer ist eine balkonsanierung

