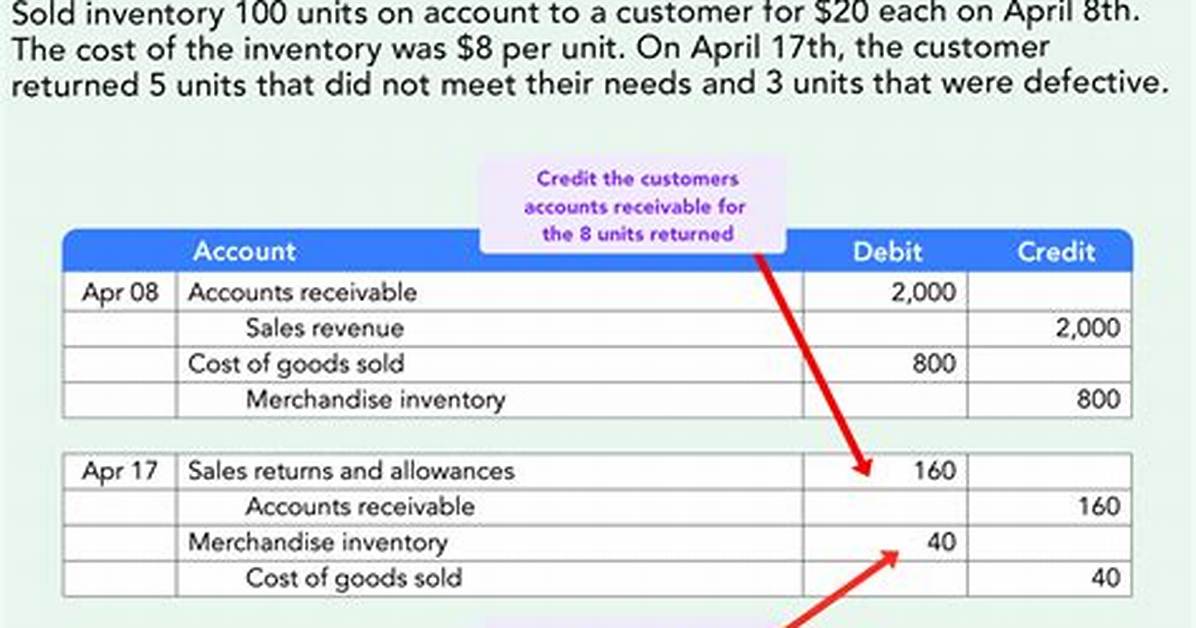
Sales returns and allowances is a line item appearing in the income statement. This line item is presented as a subtraction from the gross sales line item, and is intended to reduce sales by the amount of product returns from customers and sales allowances granted.
Is returns and allowances debit or credit?
Sales returns and allowances is a contra revenue account with a normal debit balance used to record returns from and allowances to customers. The account, therefore, has a debit balance that is opposite the credit balance of the sales account.
Are sales returns and allowances an expense?
Definition of Sales Discounts
Sales discounts (along with sales returns and allowances) are deducted from gross sales to arrive at the company’s net sales. Hence, the general ledger account Sales Discounts is a contra revenue account. Sales discounts are not reported as an expense.
What are allowances in accounting?
An allowance is a reserve that is set aside in the expectation of expenses that will be incurred at a future date. The creation of a reserve essentially accelerates the recognition of an expense into the current period from the later period in which it would otherwise have been recognized.
Are returns an expense?
Sales returns are known as a contra revenue account and they have a direct effect on the net income, thereby reducing the income. They cannot be considered as an expense but they do contribute to the loss of income. Also read: Cash Book.
What is returns and allowances on income statement?
Returns and allowances are two distinct business financial transactions that get recorded on one line of a company income statement. “Returns” is the value of the merchandise customers bring back after purchase and “allowances” is the amount of discounts you give to dissatisfied customers.
How are returns and allowances calculated?
Gross sales = 2,000 X $10,000, or $20,000,000.Discounts = $40,000 X 0.02, or $800.Sales returns = 3 X $10,000, or $30,000.Allowances = 5 X $1,000, or $5,000.Discounts + allowances + sales returns = $800 + $30,000 + $5,000, or $35,800.Net sales = $20,000,000 – $35,800, or $19,964,200.
How do you record sales returns and allowances?
Record the Sales Return Transaction
For example, if a customer returns a $100 item and the applicable sales tax rate is 7 percent, debit sales returns and allowances by $100, debit sales tax liability by $7 (0.07 x $100) and credit cash by $107 ($100 + $7).
What is purchase returns and allowances?
Purchase returns and allowances is an account that is paired with and offsets the purchases account in a periodic inventory system. The account contains deductions from purchases for items returned to suppliers, as well as deductions allowed by suppliers for goods that are not returned.
How do you record allowances in accounting?
When a supplier grants a purchase allowance, the buyer records the amount of the allowance as a debit to accounts payable and a credit to inventory. The seller records the allowance in the sales allowances account; this is a contra revenue account that is paired with and offsets gross sales.
How do you record returned goods?
When merchandise is returned, the sales returns and allowances account is debited to reduce sales, and accounts receivable or cash is credited to refund cash or reduce what is owed by the customer. A second entry must also be made debiting inventory to put the returned items back.
What are returns in accounting?
Key Takeaways. A return is the change in price of an asset, investment, or project over time, which may be represented in terms of price change or percentage change. A positive return represents a profit while a negative return marks a loss.
What are allowances on income statement?
Allowances. Include all allowances shown on your income statement or payment summary as income in your tax return. You may receive an allowance to: compensate you for an aspect of your work, for example, carrying unpleasant or dangerous goods. help you to pay for certain expenses such as meals when you travel for work.
Are returns included in revenue?
Reporting on the Income Statement
A business lists the “sales returns and allowances” account below gross revenue on the income statement and reports “net sales” below that. Net sales equals gross revenue minus the sales returns and allowances for the period.
What is an example of allowance?
Allowance is a piece of something given to a person, usually in relation to money or goods in exchange for service. An example of an allowance is the money a parent gives to a child each week for the chores they do around the house.
Is an allowance an expense?
In financial accounting, a cash allowance refers to an expense that is repaid immediately in cash, instead of being reimbursed at a later date. Employers will typically give employees cash allowances to cover incidentals and the costs of work-related expenses, such as meals, lodging, dry cleaning, and office supplies.
Are allowances an asset?
An allowance for doubtful accounts is considered a “contra asset,” because it reduces the amount of an asset, in this case the accounts receivable. The allowance, sometimes called a bad debt reserve, represents management’s estimate of the amount of accounts receivable that will not be paid by customers.

