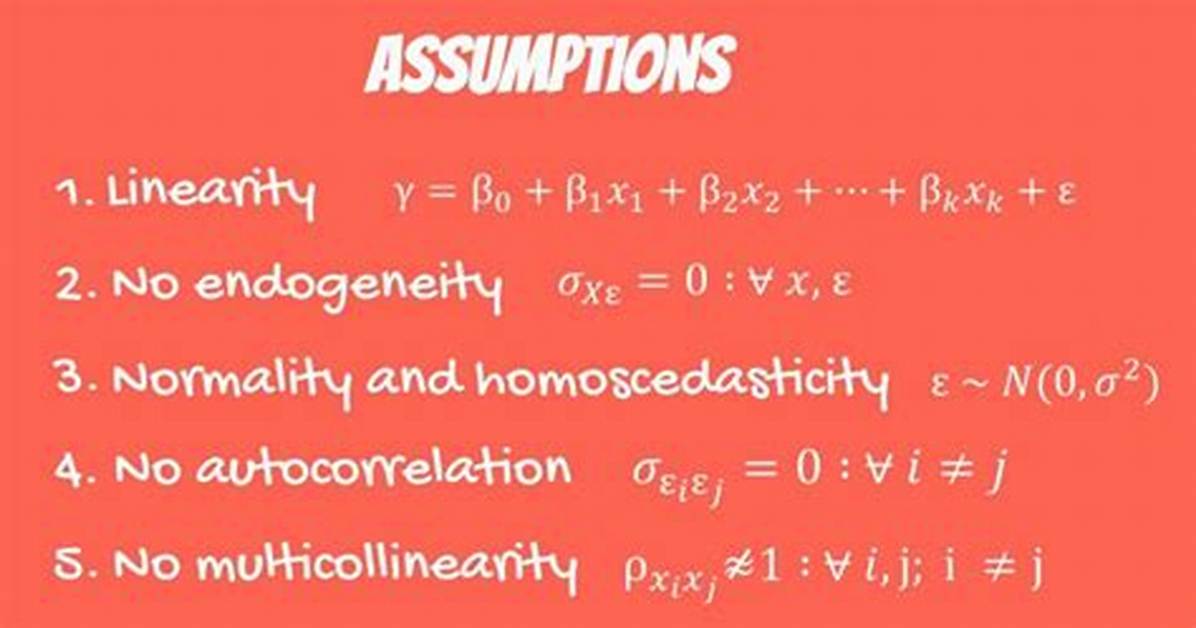
Introduction: Ordinary Least Squares(OLS) is a commonly used technique for linear regression analysis. OLS makes certain assumptions about the data like linearity, no multicollinearity, no autocorrelation, homoscedasticity, normal distribution of errors.
What is OLS and its assumptions?
OLS Assumption 1: The regression model is linear in the coefficients and the error term. This assumption addresses the functional form of the model. In statistics, a regression model is linear when all terms in the model are either the constant or a parameter multiplied by an independent variable.
What are the four assumptions behind OLS linear regression?
Linearity: The relationship between X and the mean of Y is linear. Homoscedasticity: The variance of residual is the same for any value of X. Independence: Observations are independent of each other. Normality: For any fixed value of X, Y is normally distributed.
What is the first OLS assumption?
OLS Assumption 1: Linearity
It is called linear, because the equation is linear. Each independent variable is multiplied by a coefficient and summed up to predict the value of the dependent variable.
What are the OLS estimators?
OLS estimators are linear functions of the values of Y (the dependent variable) which are linearly combined using weights that are a non-linear function of the values of X (the regressors or explanatory variables).
What is blue in OLS?
The Gauss-Markov theorem famously states that OLS is BLUE. BLUE is an acronym for the following: Best Linear Unbiased Estimator. In this context, the definition of “best” refers to the minimum variance or the narrowest sampling distribution.
What are the properties of OLS?
The unbiasedness property of OLS method says that when you take out samples of 50 repeatedly, then after some repeated attempts, you would find that the average of all the β o { beta }_{ o } βo and β i { beta }_{ i } βi from the samples will equal to the actual (or the population) values of β o { beta }_{ o } βo and
What is OLS method in econometrics?
Ordinary Least Squares regression (OLS) is a common technique for estimating coefficients of linear regression equations which describe the relationship between one or more independent quantitative variables and a dependent variable (simple or multiple linear regression).
Is OLS the same as linear regression?
Yes, although ‘linear regression’ refers to any approach to model the relationship between one or more variables, OLS is the method used to find the simple linear regression of a set of data. Linear regression refers to any approach to model a LINEAR relationship between one or more variables.
What is the difference between OLS and multiple regression?
Multiple linear regression (MLR), also known simply as multiple regression, is a statistical technique that uses several explanatory variables to predict the outcome of a response variable. Multiple regression is an extension of linear (OLS) regression that uses just one explanatory variable.
What is homoscedasticity assumption?
Homoscedasticity, or homogeneity of variances, is an assumption of equal or similar variances in different groups being compared. This is an important assumption of parametric statistical tests because they are sensitive to any dissimilarities. Uneven variances in samples result in biased and skewed test results.
What is multicollinearity in regression?
Multicollinearity occurs when two or more independent variables are highly correlated with one another in a regression model. This means that an independent variable can be predicted from another independent variable in a regression model.
Why do we use OLS estimator?
In data analysis, we use OLS for estimating the unknown parameters in a linear regression model. The goal is minimizing the differences between the collected observations in some arbitrary dataset and the responses predicted by the linear approximation of the data. We can express the estimator by a simple formula.
Why is OLS the best estimator?
Under the standard assumptions, the OLS estimator in the linear regression model is thus unbiased and efficient. No other linear and unbiased estimator of the regression coefficients exists which leads to a smaller variance. An estimator is unbiased if its expected value matches the parameter of the population.
What is the OLS objective function?
Ordinary Least Squares or OLS is one of the simplest (if you can call it so) methods of linear regression. The goal of OLS is to closely “fit” a function with the data. It does so by minimizing the sum of squared errors from the data.

