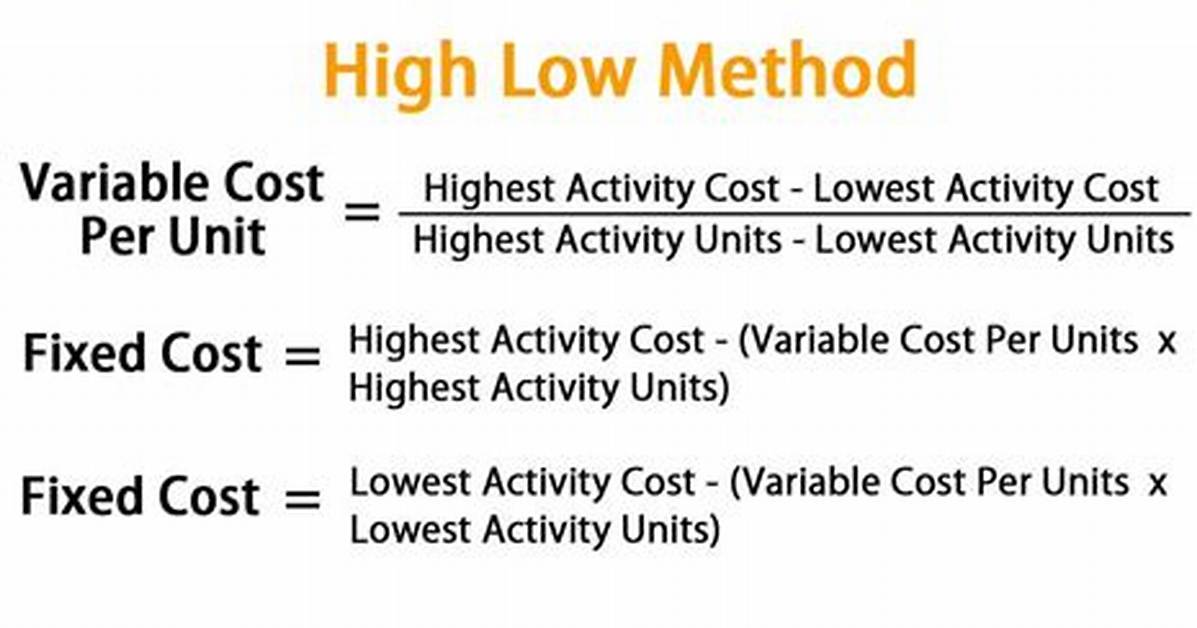
How do I calculate the fixed cost using the high-low method?
Find the highest activity cost and the highest activity unit of operation.Multiply the variable cost per unit by the highest activity unit.Subtract the product of the multiplication in step 2 from the highest activity cost.The result is the fixed cost.
How do you calculate fixed cost using high and low method?
High-Low Method Formula
Fixed cost = Highest activity cost – (Variable cost per unit x Highest activity units)Fixed cost = Lowest activity cost – (Variable cost per unit x Lowest activity units)Cost model = Fixed cost + Variable cost x Unit activity.Fixed cost = $371,225 – ($74.97 x 4,545) = $30,486.35.
What does the Hi Lo method assume?
The high-low method is an accounting technique used to separate out fixed and variable costs in a limited set of data. It involves taking the highest level of activity and the lowest level of activity and comparing the total costs at each level.
What is the formula for cost?
The formula to calculate total cost is the following: TC (total cost) = TFC (total fixed cost) + TVC (total variable cost).
How do you calculate cm ratio?
Contribution margin ratio = contribution margin / sales
(where contribution margin = sales minus variable costs). The contribution margin ratio can help companies calculate and set targets for the profit potential of a given product.
How do you calculate profit in CVP analysis?
By dividing the total fixed costs by the contribution margin ratio, the breakeven point of sales in terms of total dollars may be calculated. For example, a company with $100,000 of fixed costs and a contribution margin of 40% must earn revenue of $250,000 to break even.
What is prime cost formula?
The prime cost equation is equal to the cost of raw materials plus direct labor. Businesses need to calculate the prime cost of each product manufactured to ensure they are generating a profit.
What is the formula for finding fixed cost?
How to Calculate Fixed Cost
Fixed costs = Total production costs — (Variable cost per unit * Number of units produced)$4,000 total production costs — ($3 * 1,000 tacos) = $1,000 fixed cost.Average fixed cost = Total fixed cost / Total number of units produced.
When using high-low method What is the change in cost?
The high-low method computes the variable cost rate by dividing the change in the total costs by the change in the number of units of manufactured. In other words, the $4,800 change in total costs is divided by the change in units of 300 to yield the variable cost rate of $16 per unit of product.
What is variable cost formula?
Variable Cost Formula. To calculate variable costs, multiply what it costs to make one unit of your product by the total number of products you’ve created. This formula looks like this: Total Variable Costs = Cost Per Unit x Total Number of Units.
When using the High-Low Method What step is performed first?
Since this is called the high-low method, we first need to determine the highest point and the lowest point in the range. Because the variable rate and fixed costs are not always 100% constant, the cost should not be used.
What is the High-Low method quizlet?
high-low method is a method of separating mixed costs into fixed and variable components by using just the high and low data points. high point cost- low point cost/ high point output- low point output. high and low points are identified by looking at the activity levels and not the costs.
What is loss formula?
Loss = cost price- selling price. Loss = 50 – 45 = 5. Therefore, the loss is Rs. 5. The formula to find loss percentage is.
What is profit formula?
The profit formula is stated as a percentage, where all expenses are first subtracted from sales, and the result is divided by sales. The formula is: (Sales – Expenses) ÷ Sales = Profit formula.
What is TFC and TVC?
TC = TFC and TVC. Total fixed cost (TFC) is constant regardless of how many units of output are being produced. Fixed cost reflect fixed inputs. Total variable cost (TVC) reflects diminishing marginal productivity — as more variable input is used, output and variable cost will increase.

