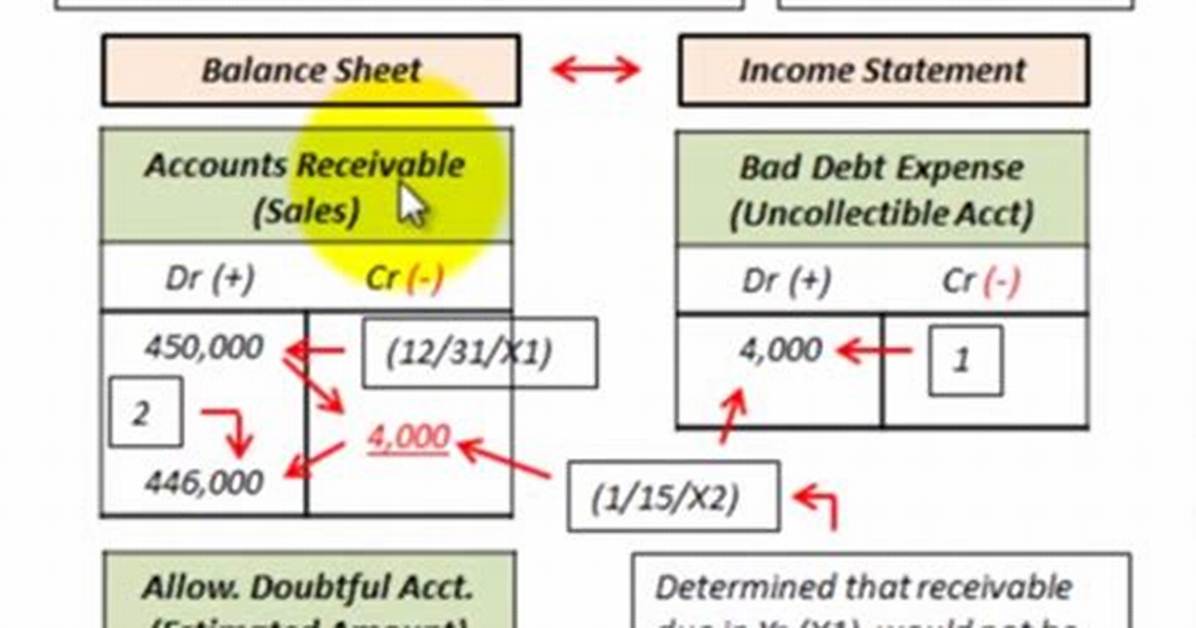
Doubtful debt is money you predict will turn into bad debt, but there's still a chance you will receive the money. Use an allowance for doubtful accounts entry when you extend credit to customers. Although you don't physically have the cash when a customer purchases goods on credit, you need to record the transaction.
How is doubtful debt recorded?
Record the journal entry by debiting bad debt expense and crediting allowance for doubtful accounts. When you decide to write off an account, debit allowance for doubtful accounts. The amount represents the value of accounts receivable that a company does not expect to receive payment for.
What is a doubtful debt example?
When there is no longer any doubt that a debt is uncollectible, the debt becomes bad. An example of a debt becoming uncollectible would be:- once final payments have been made from the liquidation of a customer's limited liability company, no further action can be taken.

