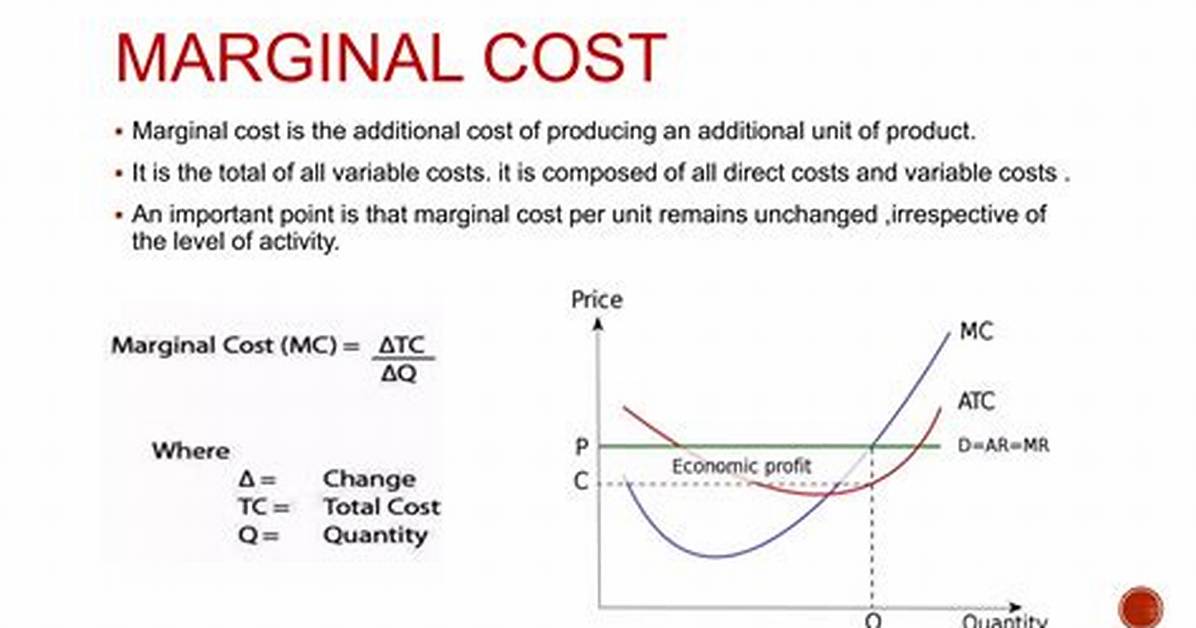
Variable cost refers to costs that change as the total level of output changes. Marginal cost refers to the additional cost incurred for producing each additional unit of the product.
How do you find marginal cost from variable cost?
The marginal cost curve is upward-sloping. Average variable cost obtained when variable cost is divided by quantity of output. For example, the variable cost of producing 80 haircuts is $400, so the average variable cost is $400/80, or $5 per haircut.
What is the relationship between variable cost and marginal cost?
The relationship between these two kinds of costs is that the change in variable costs creates the change in marginal costs. Therefore, the slope of the total variable cost curve is the marginal cost of the product.

